

Park National Bank

- 1.30K Reviews
- 4.3
- Downloads
- 100,000+
Our take on Park National Bank from Appgk
Managing a bank account from a phone should feel practical rather than complicated, and Park National Bank is built around that straightforward idea. I found it most useful as a daily companion for customers of Park National Bank who want to check their finances without opening a desktop browser or visiting a branch. It is a free finance app from Park National Corporation, rated for Everyone, and its focus is clear: mobile banking for the bank’s own customers.
My overall impression is positive, especially for someone who prefers familiar banking tools over a crowded personal-finance dashboard. The app has a 4.3 average from around 2.8 thousand ratings, with more than 100 thousand installs, so it has a meaningful user base without pretending to be a universal money-management platform. That distinction matters. This is not the right choice for somebody looking to connect accounts from many unrelated banks, build an elaborate investment plan, or replace every financial service in one place. It makes more sense when your main relationship is with Park National Bank and you want a convenient way to handle ordinary banking tasks.
What to expect from the mobile banking experience
The first thing I would tell a new user is to think of this as a secure extension of a bank account, not as a budgeting app. The value appears in small moments: checking whether a payment has cleared, confirming that a deposit arrived, reviewing recent activity before making a purchase, or dealing with an account while away from a computer. Those actions may sound basic, but they are exactly the tasks that make a mobile banking app worth keeping installed.
The app’s identity is also important. Park National Bank is not an independent wallet that anyone can use simply because it is free. Access is tied to the bank’s mobile banking service, so the smoothest experience will be for an existing customer who already knows the institution and has the necessary online banking credentials. If you are comparing apps before opening an account, I would first decide whether Park National Bank itself fits your needs; the application is a companion to that decision, not a substitute for it.
Best Parts of Park National Bank
Things to Keep in Mind About Park National Bank
On a normal day, I would use it in short sessions rather than leave it open as a financial command center. A quick glance at the account balance in the morning can prevent an avoidable overdraft decision later. Before paying a bill, I would review recent transactions and available funds. After moving money or making a purchase, I would return to the activity screen to make sure the result matches what I expected. That habit is more useful than repeatedly refreshing the app without a specific question in mind.
One subtle advantage of a bank-specific app is context. Transactions from the Park National Bank relationship are easier to interpret when they are not mixed with cards, loans, and accounts from several other institutions. The trade-off is that the app is naturally narrower than a broad finance organizer. I would choose that narrower view if clarity and direct access matter more to me than seeing my entire financial life in one dashboard.
News and Features Related to Park National Bank

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
Who will get the most from it
I think this app suits customers who already bank with Park National Bank and want a simple way to stay informed while travelling, shopping, or managing household expenses. It can also be a good fit for someone who is uncomfortable with complicated financial software. The plain purpose makes it easier to know where to begin: sign in, look at the account information, and choose the banking action you actually need.
It is less compelling for a person whose accounts are spread across several banks and who wants automatic categorization, long-term spending analysis, or a combined net-worth view. A dedicated budgeting service may be better for that job, provided the user is comfortable linking financial accounts to another platform. Likewise, someone who prefers speaking with a banker for every transaction may not gain much from installing a mobile tool, although having account information available can still be useful between conversations.
Don't want to read the full review?
Families should also think about how they divide financial responsibilities. If one person handles most banking, the app may simply make that person’s routine faster. If several people need coordinated visibility, the important question is not only whether the app is convenient, but whether the account access arrangement already reflects the family’s needs. I would settle that expectation before relying on a phone as the main way to manage shared money.
Getting from installation to a useful first result
Start with the right account details
After installing Park National Bank, I would avoid rushing through the first screen just to see what is inside. The most reassuring setup is to have the online banking sign-in information ready and to use the same details associated with the bank account. Entering information carefully is especially important with financial apps because repeated failed attempts can turn a simple first visit into a frustrating security problem.
Screenshots
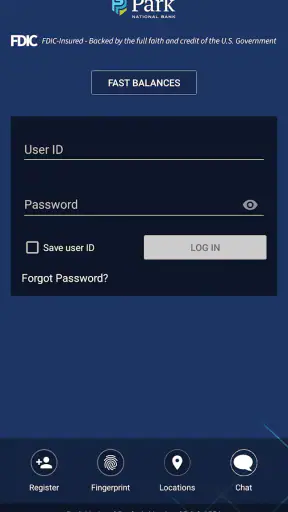
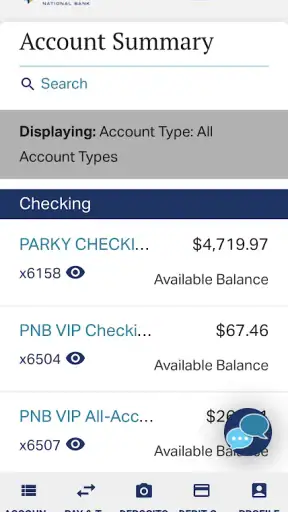
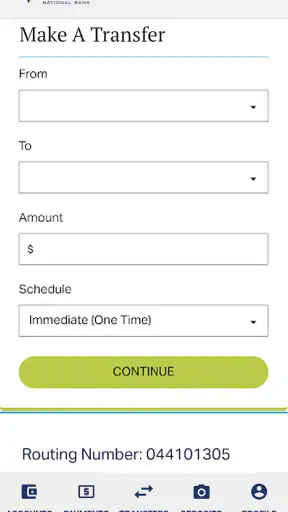
I would also set up the app when I have a few quiet minutes, rather than while standing in a checkout line. A first sign-in is a poor task to combine with distractions, a weak connection, or an urgent payment. Taking a moment to confirm that the account name and visible balance make sense gives me a baseline. If something looks unfamiliar at that stage, I would stop and resolve it before attempting any transaction.
The current version is 25.2.0 and requires iOS or Android 11, so checking that the phone meets the minimum operating-system requirement is a sensible first step. That is a small detail, but it prevents the common mistake of assuming that every banking app will run on an older device. I also prefer using an up-to-date phone lock and avoiding sign-in over an unsecured public network when handling sensitive account information.
Make the first session observational
For a first meaningful success, I would begin with something that does not change the account: sign in and identify the current balance and recent activity. This gives a new user a safe tour of the information they will probably consult most often. I would compare one or two recent entries with receipts, email confirmations, or my own memory, not because every difference signals a problem, but because recognizing the transaction layout makes later visits faster.
This is also where I would learn the difference between a balance that is displayed and money that is genuinely available for a new purchase or payment. Banking screens can show activity at different stages, and a pending card purchase may not behave like a completed transaction. I would not make a large financial decision based on a quick glance alone. If the amount matters, I would read the transaction details carefully and allow for normal processing time.
That simple review is more valuable than immediately exploring every menu. It answers the first question most users have—“Can I see what is happening in my account?”—and establishes confidence before money is moved. Once the screen feels familiar, the app becomes less intimidating because future sessions start from a known point.
Use a small, low-risk task to build confidence
When I was ready to do more, I would choose the smallest routine action relevant to my account rather than testing the app with an important payment. For example, I might review a known transaction or prepare to handle an ordinary banking task that I already understand from using the bank’s other channels. The goal is not to experiment with money; it is to confirm that the mobile workflow matches my expectations.
Before submitting anything that changes an account, I would check the destination, amount, timing, and confirmation message. I would take a screenshot only for my own records if appropriate, while remembering that a screenshot is not the same as proof that a transaction has fully completed. The most useful habit is to return later and verify the resulting activity rather than assuming that tapping a button ended the process.
This two-stage approach—observe first, then perform a familiar task—helps answer a question many first-time users have: is the app difficult to learn? In my experience, the difficulty is less about the number of screens and more about the seriousness of banking actions. Moving slowly is a strength here. A few extra seconds spent checking details are preferable to correcting an avoidable mistake.
Common points of confusion
The biggest source of confusion is usually timing. A transaction can be visible without being final, and an account balance can change at a different moment from the user’s mental record of a purchase. I would treat the activity list as a record to interpret, not as a promise that every item has settled. If a purchase appears twice, disappears, or shows an unexpected status, I would first consider whether one entry is still processing before assuming the bank has charged me twice.
Another common issue is expecting a mobile banking app to behave like a budgeting service. Park National Bank is useful for viewing and managing the banking relationship it represents, but I would not install it expecting a full spending-coach experience. If I wanted detailed categories across multiple institutions, I would use a separate tool designed for that purpose and keep the bank app for direct account access.
Users may also wonder whether the app replaces customer support or a branch. I would view it as an additional channel, not a complete replacement for every banking conversation. A phone is excellent for checking information and handling routine needs, but a complicated account question, disputed activity, or situation requiring identity verification may still be better handled through the bank’s established support options.
There is also a practical device question. If a phone is shared, lost, or frequently borrowed by other people, I would be more cautious about leaving a banking session accessible. A strong device passcode and careful sign-out habits matter more than any attractive interface. I would never treat the convenience of mobile access as a reason to weaken basic security routines.
Three habits that make the app more useful
First, I would use the app as a checkpoint before spending, not merely as a place to investigate problems afterward. A quick review before a large purchase can reveal a pending payment or an account change that is easy to forget. This is especially helpful when several recurring charges arrive close together and my own mental estimate is no longer reliable.
Second, I would verify important actions twice: once immediately after submitting them and again when the activity reflects the completed result. The first check confirms that I entered the details correctly; the second separates a submitted request from a settled transaction. That distinction is easy to overlook and is one of the most useful habits for anyone new to mobile banking.
Third, I would keep the app’s role deliberately narrow if I already use another financial tool. Rather than duplicating every note and category, I would let Park National Bank serve as the source I consult for the bank account itself. This reduces conflicting records and makes it clearer which screen should answer a particular question. The trade-off is that I may need another app for broader analysis, but the division of labor is cleaner.
How it compares with familiar alternatives
Compared with visiting a branch, the app is more convenient for quick checks and routine moments when travelling or outside business hours. A branch remains the better setting for a detailed conversation, reassurance about a complicated issue, or help from someone who can guide the process directly. I would not judge the app harshly for not replacing that human interaction; its strength is speed and access.
Compared with a desktop banking website, a phone app feels better suited to short checks. A larger screen can be more comfortable when reviewing a long history or managing several pieces of information at once, while the mobile version is easier to reach when I need a fast answer. I see them as complementary rather than competing tools.
Compared with an independent budgeting app, Park National Bank offers a more focused relationship with the bank itself. That can mean less clutter and fewer connected services, which I appreciate when I only need account information. The compromise is reduced usefulness for someone who wants a complete picture across banks, cards, investments, and household categories. Choosing between them depends on whether direct banking access or broad financial analysis is the immediate priority.
What I would do next after the first successful session
Once I had signed in, checked recent activity, and completed a familiar low-risk task, I would create a personal routine around the app instead of opening it randomly. I might check it before major spending, after an expected deposit, and whenever an account activity notification or receipt gives me a reason to confirm the record. Short, purposeful visits are less stressful than constantly monitoring the account.
I would also keep expectations realistic about version changes. Park National Corporation has continued developing the app, and the current release is 25.2.0, but an update number alone does not tell me how every screen will behave on my particular phone. After an update, I would take a moment to locate the functions I use most and avoid attempting an important transaction until the layout feels familiar again.
Park National Bank first appeared on May 7, 2013, and its continued presence as a mobile banking option gives it the feel of an established companion rather than a novelty. Still, longevity does not remove the need for sensible habits: protect the phone, review transaction details, and contact the bank when something genuinely needs clarification.
My final recommendation is fairly specific. If you are a Park National Bank customer who wants convenient access to everyday account information and routine mobile banking, I think this free app is worth trying. Its 4.3 average and broad installation base suggest that many users find the basic experience dependable, but I would not mistake that for a promise that it will satisfy every financial need. Its best quality is focused usefulness: it helps me stay connected to my Park National Bank account without turning a simple check into a complicated financial project.
I would skip it as my main finance tool if my priority is cross-bank budgeting, deep spending analysis, or a single dashboard for every financial product. In that case, a broader alternative will probably serve me better, while this app may still be useful as the direct window into the Park National Bank relationship. For a first-time user, the safest path is clear: install it on a compatible device, sign in carefully, inspect the account before changing anything, and let one familiar successful action establish confidence.
Park National Bank FAQ
What is Park National Bank, and what can I do with its mobile app?
Park National Bank’s mobile app is designed to give customers convenient access to everyday banking services from an Android or iOS device. After signing in, you can typically review account balances and transaction history, transfer money between eligible accounts, pay bills, deposit checks remotely, manage alerts, and locate nearby branches or ATMs. Available tools may depend on your account type and region.
Is the Park National Bank app safe to use for mobile banking?
The app uses standard banking security practices, including secure sign-in and encrypted communication, to help protect your financial information. You should still use the latest version of your phone’s operating system, avoid public Wi-Fi when possible, and never share your password or verification codes. Enable biometric login or additional security options if they are offered on your device.
Can I deposit checks through the Park National Bank mobile app?
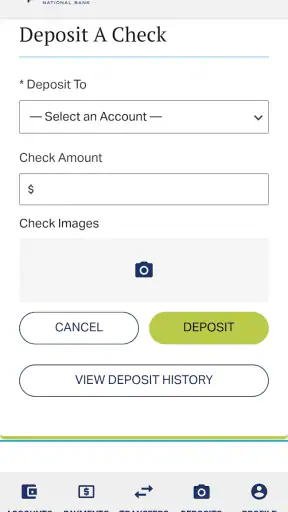
Eligible customers may be able to deposit checks by photographing the front and back of each check with the app. Before submitting a deposit, endorse the check as instructed, make sure the images are clear, and verify the account and amount. Deposit limits, availability times, fees, and eligibility can vary, so review the app’s instructions and retain the check until the deposit is fully processed.
Does Park National Bank’s app support bill payments and money transfers?
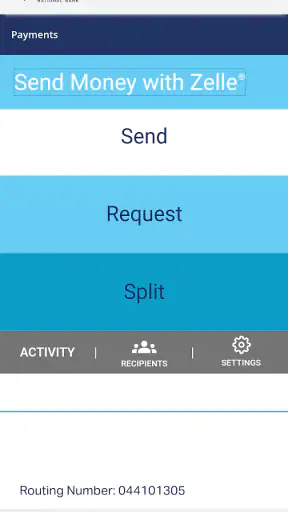
The mobile banking experience generally provides tools for moving money and managing payments, such as transfers between linked Park National Bank accounts, eligible external accounts, and scheduled bill payments. Some features may require enrollment or additional verification, while transfer timing can depend on the payment method and recipient. Check the confirmation screen carefully before submitting any transaction.
What should I do if I cannot log in to the Park National Bank app?
If you cannot access your account, first confirm that your internet connection is working and that you are entering the correct credentials. Use the available password-reset or username-recovery option rather than repeatedly guessing. Updating or reinstalling the app may resolve technical problems, but contact Park National Bank through an official website, branch, or verified support number if the issue continues. Never rely on unsolicited messages requesting login details.











